
Remember all the talk last summer about writing off car loan interest? It didn't disappear. It just got a new name. The savings everyone called the Big Beautiful Bill auto loan break are now part of what the IRS calls the Working Families Tax Cuts, and the details have become much clearer since then. Here at GMC of Riverfront Park in Spokane, it comes up in nearly every finance conversation we have, so we put the answers in one spot.
Key Takeaways
- ✔ Same law, new name: you can deduct up to $10,000 a year in qualifying interest on a new-vehicle loan for tax years 2025 through 2028.
- ✔ You don't need to itemize. The deduction goes on Schedule 1-A, along with your vehicle's VIN.
- ✔ The vehicle must be new, under 14,000 pounds GVWR, mainly for personal use, and have its final assembly in the U.S.
- ✔ The deduction shrinks above $100,000 MAGI (single) or $200,000 (joint) and disappears at $150,000 or $250,000.
- ✔ Starting with the 2026 tax year, qualifying borrowers should get a new Form 1098-VLI from their lender showing the interest paid.
What's Different About the Big Beautiful Bill Auto Loan Tax Deduction Now?
The core rules haven't moved. The law was signed on July 4, 2025, and the Big Beautiful Bill auto loan tax deduction still covers interest on loans taken out after 2024. What's changed is the name on the label and a handful of helpful clarifications:
- ✔ A new form. For 2026 and later, lenders should send Form 1098-VLI by January 31 if you paid at least $600 in qualifying interest.
- ✔ Add-ons can count. Interest on financed items tied to the purchase, such as sales tax, title and registration, dealer fees, an extended warranty, a service plan, or accessories added at the sale, is typically deductible as well.
- ✔ Refinancing is generally okay, as long as the original loan qualified and the new one stays secured by a first lien on the same vehicle.
- ✔ Demo miles aren't a dealbreaker. Test drives or loaner use don't automatically make a vehicle "used," but it won't count if the dealer titled or registered it first.
Does My Car Qualify for the Car Loan Interest Deduction?
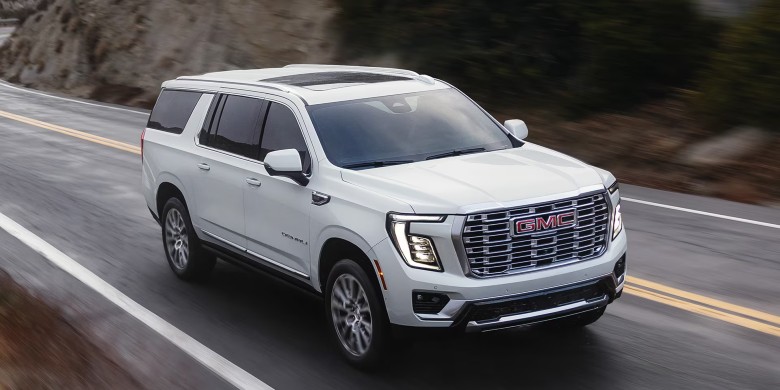
It's the question we hear most: does my car qualify for the car loan interest deduction? Start with the basics. It needs to be a new car, SUV, pickup, van, minivan, or motorcycle with a GVWR under 14,000 pounds. Used vehicles don't count, even if they're new to you. Leases don't count, and neither does financing a lease buyout. You also need to expect, at the time of the loan, to drive it for personal reasons more than half the time. Loans from a relative are out, too.
Then comes final assembly in the U.S. Parts can come from anywhere, but the finished vehicle has to roll off an American line. The window sticker lists the final assembly point, and you can also run the VIN through NHTSA's free decoder. Not sure about the one you're eyeing? Our team will gladly check it with you before you sign anything!
How Does the Car Loan Interest Deduction Phase Out?
The car loan interest deduction phase-out starts once your modified adjusted gross income exceeds $100,000 if filing single or $200,000 if filing jointly. For every $1,000 over (rounded up), the deduction drops by $200.
Say you're single, paid $12,000 in interest, and have a MAGI of $120,600. Your deduction is capped at $10,000 first. You're $20,600 over the threshold, which rounds up to 21, and 21 times $200 is $4,200. That leaves $5,800. By $150,000 single or $250,000 joint, it's gone. Keep in mind this is a deduction, not a credit, so it lowers taxable income rather than your tax bill dollar for dollar.
How Do You Claim the Working Families Tax Cut Auto Loan Savings?
Watch for that lender statement, then report the interest on Schedule 1-A with your VIN, whether you take the standard deduction or itemize. Paying off two qualifying loans? You can combine the interest, but the yearly cap stays at $10,000. And there's no price limit on the vehicle itself. That flexibility is what makes the car loan interest deduction so useful for everyday buyers. We're a GMC dealership, not a tax firm, so check with your tax professional about your own situation.
Making the Tax Break Work for Spokane Drivers
The Working Families Tax Cut auto loan savings are real, but they're temporary and will wrap up after the 2028 tax year. Our honest take? The best purchases are the ones where the tax break is a bonus, not the whole reason to buy. If a new Sierra, Canyon, or Yukon already fits your life on Inland Northwest roads, this simply makes the math friendlier. Stop by GMC of Riverfront Park and our finance team will walk you through your options, VIN check included.
Frequently Asked Questions
Is the Working Families Tax Cuts deduction the same as the Big Beautiful Bill one?
Yes. It's the same law signed in July 2025. The IRS now refers to it as the Working Families Tax Cuts.
Can I deduct interest on a leased vehicle?
No. Lease payments don't qualify, and a loan to buy out a lease doesn't either, since the vehicle isn't considered new at that point.
Do I need to itemize to claim it?
Nope. It's a below-the-line deduction, so you can claim it with the standard deduction or itemized deductions.
Can I still claim it if I drive for Uber or Lyft?
Possibly. If you expected to use the vehicle more than 50% for personal driving when you took out the loan, it can still qualify.
How long will the deduction last?
As the law stands, it covers tax years 2025 through 2028.
GMC of Riverfront Park
Address: 636 E Sprague Ave, Spokane, WA 99202
Phone: (509) 209-9966
Hours of Operation:
- Monday - Saturday: 9:00 AM – 7:30 PM
- Sunday: 10:00 AM – 6:00 PM